A complaint against the real estate bank in Saudi Arabia begins when a practical problem appears in the support, the application, the finance or the collection. The problem may be a support payment that has not arrived, a refused eligibility, an unclear deduction, or an inadequate reply from the financing bank.
The most common mistake is sending the complaint to a body that cannot resolve the problem. The Real Estate Development Fund is not the Sakani platform, the financing bank is not responsible for everything related to support, and the Central Bank usually enters where there is a dispute with a financial institution.
So do not escalate before identifying the type of problem and the competent body. Arranging the route from the start can save time and make your request clearer when you follow up, especially where the file involves documents, amounts or an earlier reply.
If your question concerns eligibility and obligations before any problem arises, understanding the conditions for real estate loans in Saudi Arabia helps you tell whether the route needs a data correction or an actual complaint.
Unsure which body should receive your complaint?
Support, eligibility, finance and collection problems go to different bodies. A BMS Legal lawyer in Jeddah can give your documents an initial review before you file a complaint or an objection.
Enquiries are handled confidentially · No specific court outcome can be guaranteed
Your Quick Guide: Who Is Responsible for Your Problem?
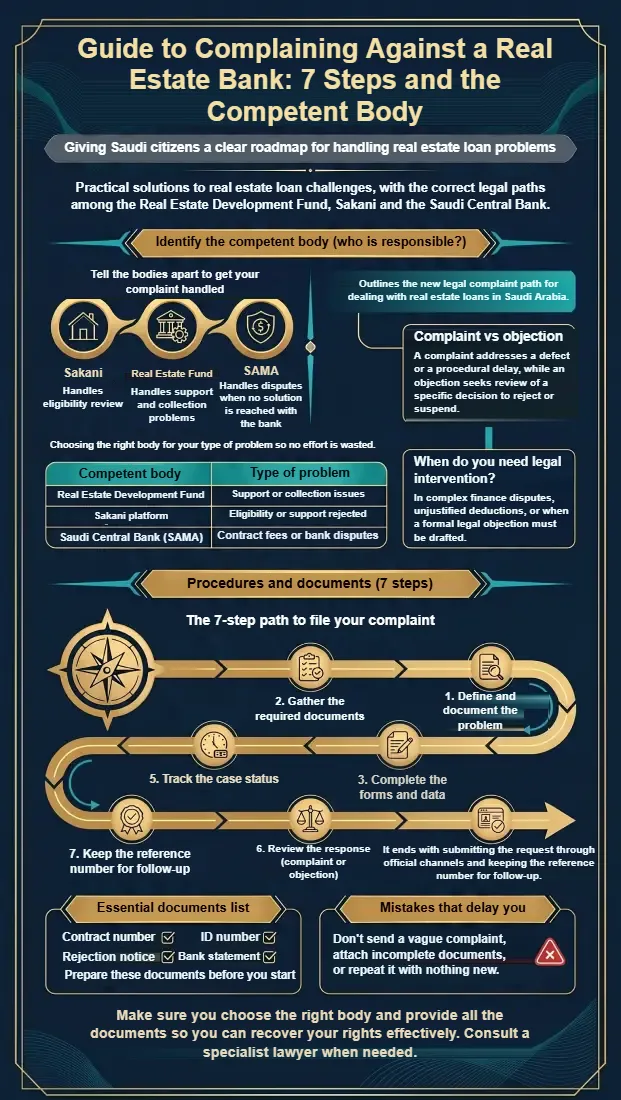
If the problem is in the monthly support or a delayed deposit, it usually starts with the Real Estate Development Fund. If it is in eligibility or the application status before finance, the closest route is the Sakani platform. If it is in the instalment, fees or the finance contract, start with the financing bank, then escalate if needed.
| Type of problem | Closest body | What to review first |
|---|---|---|
| Support has not arrived | The Real Estate Development Fund | The support status and account statement |
| Eligibility refused | The Sakani platform | Application data and eligibility |
| An unclear deduction or instalment | The financing bank | The finance contract and repayment schedule |
| Collection of a direct loan | The Real Estate Development Fund | The collection or deduction notice |
| A complaint the bank did not resolve | The Saudi Central Bank | The bank’s complaint number and reply |
If the defect is in eligibility or in the application data before finance, it is better to review the requirements of the real estate bank in Saudi Arabia before building a complaint that may not be addressed to the right body.
What Does a Complaint Against the Real Estate Bank Mean?
A complaint against the real estate bank is a documented request made by the beneficiary to address a defect connected with support, eligibility, finance, collection, or a body’s reply to an earlier request. The phrase does not always mean the complaint goes to a single body.
Many people use the phrase “real estate bank” to refer to the Real Estate Development Fund, the financing bank or the housing-support services. Understanding the key differences between a loan and real estate finance helps you tell whether the problem lies with the support body or with the finance contract before you write the complaint.
The strongest wording is direct and specific. For example, you can write: support was not deposited for a stated month; or the application was refused although the documents were complete; or there is an unclear deduction in the finance contract.
When you describe the incident clearly, directing the request becomes easier. A general complaint may bring a general reply that does not deal with the root of the problem, especially if the chosen body is not competent.
When Do You Complain to the Real Estate Fund?
Submit the complaint to the Real Estate Development Fund when the root of the problem concerns support, collection or direct loans. Examples include delayed real estate support, a difference in the deposited amount, support stopping without a clear reason, or a note on a deduction or collection.
Not every case needs a long complaint. If the matter is a simple enquiry, contacting the official channel may be enough. If there is an amount, a suspension of support, or an earlier reply that is unclear, it is better to submit a documented request with the supporting papers.
A complaint may need more careful drafting where you hold a written decision or result. Here you must tell a complaint from an objection: a complaint asks for a defect to be put right, while an objection reviews a specific decision or a result you reject.
If you are looking for how to file a complaint with the Real Estate Fund, start by identifying the problem before opening the form. A clear request starts from the incident and the documents, not from a general description that does not say what is being asked.
How to File a Complaint With the Real Estate Fund
Filing a complaint with the Real Estate Fund starts with preparing your data and then submitting the request through the official channel. Do not start writing before you gather the application or contract number, the date of the problem, and the document that proves the incident.
Write a clear summary explaining what happened, when it happened, and the result you ask for. Avoid emotional wording or general accusations, because the strongest complaint links the incident to a document, a date or a request number.
Follow these steps before sending the complaint:
- Identify the type of problem: support, collection, deduction, or an earlier reply.
- Prepare your ID number and the application number or finance contract.
- Attach the account statement, the refusal notice or the correspondence.
- Write the final request in clear, specific words.
- Submit the complaint through the suitable official channel.
- Keep the reference number and the date of sending.
- Follow up through the same channel before moving to escalation.
A phone complaint is useful for an enquiry or to learn the right channel. If the subject concerns an amount, a refusal or a suspension of support, it is better for the request to be written and documented.
Complaint Numbers and Contact Channels
Searching for the real estate bank’s complaint number usually means the beneficiary wants a fast solution. But a number alone is not enough in every case, because an enquiry differs from a financial complaint or an objection to a decision.
The Real Estate Development Fund publishes its contact channels on its official contact page, including a unified number and a number for direct loan collection services. Use the channel that fits the type of problem, and do not mix a support enquiry with following up a collection. The numbers can change, so take them from the official page rather than from a third-party source.
If the problem is with the financing bank, begin with the bank’s own complaint channels. Keep the complaint number and the institution’s reply, because escalating to the Central Bank usually needs a statement of what happened with the financial body first.
Use a call when you want to learn the right route or follow the status of a request. Use a written complaint when you have documents, amounts, an earlier reply, a suspension of support, or a dispute that needs to be documented.
When Does the Complaint Go Through Sakani?
The complaint goes through Sakani when the problem concerns eligibility, entitlement, the application status, the beneficiary’s data, or services linked to housing products. If the problem appears before the finance is signed, the bank or the Fund may not be the right starting point.
Examples include a status of “not eligible”, a problem in the application data, or an unclear reason for refusal. In these cases, first review the application route on Sakani, then collect what proves the correction or the objection.
Sakani also offers a beneficiary care centre and other support channels depending on the services available, which you can find on its official platform. What matters more than the number is deciding whether the problem is in eligibility or in finance or support.
Ask yourself before submitting: did the problem appear before or after signing the finance? If before, it is usually tied to Sakani. If after, it may move to the Fund or the financing bank depending on the incident.
When Do You Complain Against the Financing Bank or Through the Central Bank?
If the problem is in the finance contract, the instalment, the fees, the profits, early repayment or a deduction, the start is with the financing bank. The bank is a party to the financial contract, not just a channel connected to the support.
Begin with a clear complaint to the bank and ask for a reference number or a written reply. If the matter is not resolved, or the reply is inadequate, you can escalate to the Saudi Central Bank against a financial institution under its supervision.
A real estate finance complaint to the Central Bank is suitable where the dispute concerns the bank or the finance company. Examples include unclear fees, a difference in the instalment, a delay in processing the request, or not being given a document connected with the product.
Complaint, Objection and Grievance: What Is the Difference?
A complaint asks for a defect or problem to be dealt with, such as a delay in support, an unclear deduction, or a request not processed. An objection is usually linked to a specific decision, such as a refusal, a suspension, or a result you disagree with.
A grievance is more formal than a complaint and appears when you want a decision reviewed within a defined route. These terms should therefore not be treated as one thing, because each directs the request differently.
If the problem is a delay or an error in processing, write a direct complaint. If you have a refusal or suspension decision, the closer course is a documented objection that explains the decision, the reason and the documents.
Where there is a clear decision that needs organised drafting, a separate objection letter can be prepared instead of placing a long template inside the complaint. What matters is that your request is specific and consistent with the nature of the reply or decision.
Documents to Prepare Before Filing the Complaint
The strength of a complaint comes not from the length of the text but from the clarity and order of the documents. Before filing, gather what directly proves the incident, and do not attach many files that do not serve the subject of the request.
| Type of problem | Suitable document | Purpose of attaching it |
|---|---|---|
| Support not paid | Account statement and application status | Proving non-deposit in the period |
| Support stopped | Suspension notice or earlier correspondence | Knowing the reason and date of the stop |
| A deduction | Account statement and repayment schedule | Clarifying the amount and date |
| A finance dispute | Finance contract and the bank’s reply | Defining the point of dispute with the institution |
| Refusal or objection | Refusal decision and the documents | Building a clear review request |
Keep a copy of every request you send, the complaint number, and the date of filing. These details help when you follow up or escalate, and they prevent you having to explain the problem from the start each time.
Not sure which body should receive your complaint?
The Fund, Sakani, the financing bank and the Central Bank each deal with different problems. Identify the type of problem and gather your documents before you file, so the request reaches the right body.
Enquiries are handled confidentially · No specific court outcome can be guaranteed
Mistakes That Weaken a Real Estate Bank Complaint
The commonest mistake that weakens a complaint is sending it to the wrong body. If the problem is in eligibility and you take it to the bank, or it is in fees and you take it to the Fund, you may receive a reply that does not deal with the root of the problem.
Another mistake is writing a general complaint with no clear request. Do not write only “please solve the problem”: state the incident, the date, the body, the documents and the result you want from the request.
Avoid repeating the same complaint without new information. If you have already filed a request, give its number and add the earlier reply or the new document, instead of opening several requests with the same text.
And do not neglect to save the reference number; it is the means of follow-up and escalation. Losing it makes the timeline unclear, especially if the problem is financial or linked to an earlier reply.
When Do You Need a Lawyer?
You do not need a lawyer for every simple complaint, but legal review becomes important when the complaint has a financial effect or an overlapping route. That is the case with collection, deductions, a significant refusal, a finance dispute, or an objection that needs careful drafting.
The lawyer’s role here is not to explain loan conditions or finance types again. The more important role is to identify the competent body, read the documents, draft the request, and assess whether the route is administrative, financial or judicial.
Where there is a financial deduction, a finance dispute or a significant refusal, advice from a real estate lawyer in Jeddah helps arrange the documents and identify the competent body before an incomplete objection is filed.
If a complaint against the real estate bank turns into a financial dispute or a significant objection, do not rely on a general template. The drafting must suit the body, the decision and the available documents.
Trust and Legal Basis
Trust and Legal Basis
Legal basis
This guide is based on the official contact pages of the Real Estate Development Fund and the Saudi Central Bank listed below, and is written for general legal awareness rather than as advice on a specific case. Contact channels and procedures can change, so confirm them on the official pages before you rely on them.
Published by: BMS Legal Law and Legal Consultancy Company.
Address: Jeddah, Al-Mishrifah District, Palestine Street, Al-Safeer Tower
Frequently Asked Questions About a Complaint Against the Real Estate Bank
How do I file a complaint against the real estate bank?
Identify the type of problem, choose the competent body, prepare the documents, and submit the request while keeping the complaint reference number.
Is the real estate bank the same as the Real Estate Development Fund?
The "real estate bank" is a common name among people, while the Real Estate Development Fund is the official name of the body connected with support.
When do I complain to the Real Estate Fund?
When support is delayed or stopped, when there is a problem with a deduction, or when a defect is tied to the Fund's services.
What should I do if the real estate support has not arrived?
Check the application status first, then file a documented complaint and attach an account statement or proof that the support was not deposited.
When is the complaint made through Sakani?
It is made through Sakani when the problem concerns eligibility, entitlement, the application status or the beneficiary's data.
When do I escalate to the Central Bank?
When the problem is with a bank or finance company, especially over the contract, fees or a deduction, and the complaint was not resolved or the reply was inadequate.
Conclusion
A complaint against the real estate bank in Saudi Arabia, with its seven steps and the competent body, is not just a title; it is a way of thinking before any step. When you know the right body, hold your documents and write your request clearly, your route becomes more orderly and less scattered between the Fund, Sakani and the financing bank.
Before filing, identify the type of problem first: support, eligibility, finance, collection or deduction. Then choose the competent body, collect the documents, and write a short request explaining the incident and the result you ask for.
If you hold documents or an earlier reply and need an initial assessment of the route, contact BMS Legal in Jeddah with a brief description of the case, without sharing sensitive data at first.
Deduction, refusal or a finance dispute?
Send us a short description and your documents, and a BMS Legal lawyer in Jeddah will tell you which body to approach and what to attach first.
Enquiries are handled confidentially · No specific court outcome can be guaranteed
Official Legal and Government Sources
- Real Estate Development Fund: contact and support page (official website)
- Saudi Central Bank: electronic services (Arabic-language official page)
Disclaimer: This article is for general legal awareness and is not advice on an individual case, and reading it does not create a lawyer–client relationship. The legal assessment varies with the facts, the documents and the rules that apply to each case.